Help To Buy Or Shared Ownership
So, you're thinking of buying a home, but the whole process seems like a daunting task? You're not alone! Many people struggle to get on the property ladder, but what if there...
So, you're thinking of buying a home, but the whole process seems like a daunting task? You're not alone! Many people struggle to get on the property ladder, but what if there were ways to make it easier and more affordable?
Let's talk about Help to Buy and Shared Ownership - two schemes that can help make your dream of owning a home a reality. But, what's the difference between them, and which one is right for you? Think of it like choosing between a rough guide and a personalized map to help you navigate the world of home buying.
What is Help to Buy?
Help to Buy is a government scheme that allows you to buy a new-build home with just a 5% deposit. The government will then lend you up to 20% of the purchase price, interest-free for five years. It's like having a trustworthy sidekick to help you out with the costs!
Must Read
But, how does it work, you ask? Well, imagine you're buying a £200,000 home - you'll need a £10,000 deposit, and the government will lend you £40,000. You'll then need to get a mortgage for the remaining £150,000. It's like doing a puzzle, and Help to Buy is the missing piece that makes it all fit together!
The Benefits of Help to Buy
The benefits of Help to Buy are pretty appealing - you'll need a smaller deposit, and your mortgage payments will be lower. It's like having a weight lifted off your shoulders! You'll also have more flexibility to choose the home you want, rather than being limited by your budget.
But, what about the catch? Well, there are some restrictions on the types of homes you can buy, and you'll need to meet certain eligibility criteria. It's like playing a game - you need to follow the rules to win!
 Mortgages For Second Time Buyer Explained
What is Shared Ownership?
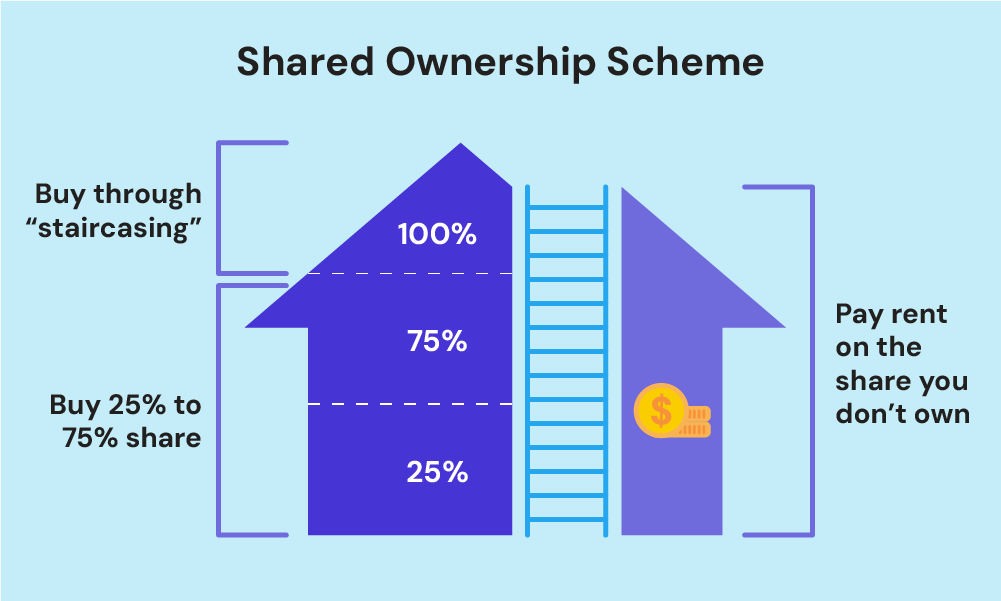
Shared Ownership is another way to get on the property ladder - you'll buy a share of a home, usually between 25% and 75%, and pay rent on the remaining share. It's like being a part-owner of a home, rather than a full owner!
But, how does it work, you ask? Well, imagine you're buying a £200,000 home, and you purchase a 50% share. You'll pay £100,000 upfront, and then pay rent on the remaining £100,000. It's like having a partner in the home-buying process - you'll share the costs and the responsibilities!
The Benefits of Shared Ownership
The benefits of Shared Ownership are pretty tempting - you'll have lower upfront costs, and your monthly payments will be more affordable. It's like having a safety net to catch you if you fall! You'll also have the opportunity to increase your share of the home over time, which can be a great investment!
 Who Is A First-time Buyer?
But, what about the downsides? Well, you'll need to pay rent on the share you don't own, and you might have restrictions on what you can do with the property. It's like playing a game of chess - you need to think carefully about your moves!
So, which one is right for you - Help to Buy or Shared Ownership? It's like choosing between a fast car and a reliable bike - both will get you where you want to go, but one might be more suited to your needs! Ultimately, it comes down to your personal preferences and financial situation.
Both schemes have their pros and cons, but they can be a great way to get on the property ladder. It's like having a map to guide you through the process - you'll still need to navigate the twists and turns, but you'll have a better idea of where you're going! So, which one will you choose - the helping hand of Help to Buy, or the partnership of Shared Ownership?
